Earning more can be a great sign of career or business progress, but it can also raise questions about how much of your additional income you will actually keep.
If your taxable income moves into the UK’s higher-rate band, you may start paying Income Tax at 40% on part of your income. However, being in the 40% tax bracket does not mean that 40% of your entire salary is taken in tax.
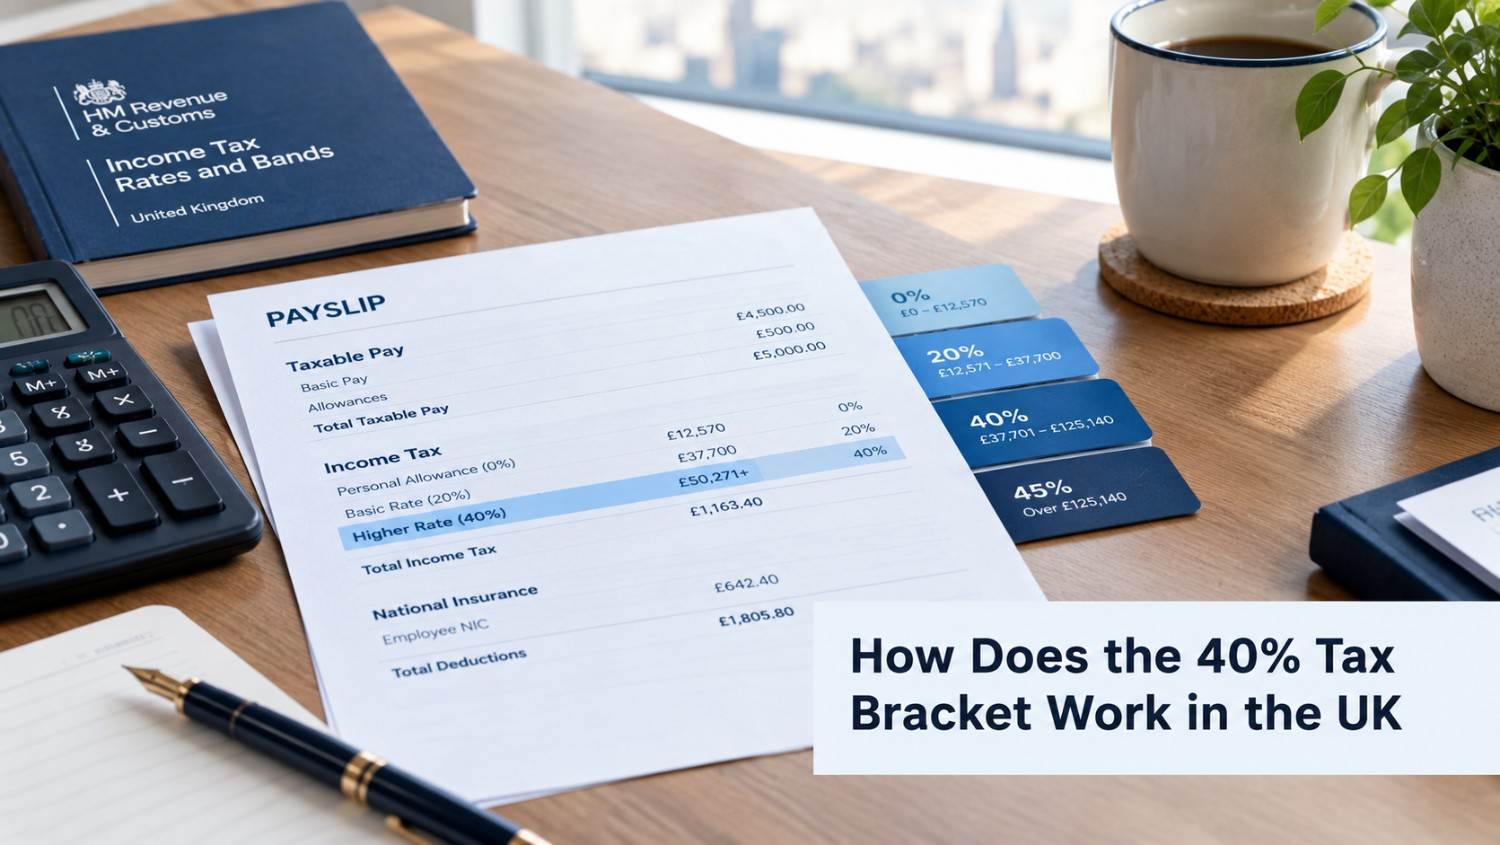
For the 2026/27 tax year, the standard Personal Allowance is £12,570. In England, Wales and Northern Ireland, the higher-rate band applies to taxable income from £37,701 to £125,140 after allowances.
The 40% tax bracket, also known as the higher-rate tax band, is the Income Tax band that applies to certain levels of taxable income.
For the 2026/27 tax year in England, Wales and Northern Ireland, the main Income Tax bands are:
|
Tax band |
Taxable income |
Rate |
|
Personal Allowance |
Up to £12,570 |
0% |
|
Basic rate |
Up to £37,700 after allowances |
20% |
|
Higher rate |
£37,701 to £ 112,570 after allowances |
40% |
|
Additional rate |
Above £125,140 |
45% |
These thresholds apply to relevant non-savings and non-dividend income. Scotland has different Income Tax bands and rates, so Scottish taxpayers need to use the Scottish thresholds when calculating their Income Tax.
One of the most common misunderstandings about the 40% tax bracket is thinking that someone who enters it pays 40% tax on all their income.
That is not how a progressive tax system works.
Different portions of your taxable income are taxed at different rates. For example, assuming you have the standard £12,570 Personal Allowance and no other adjustments:
The Personal Allowance can also be reduced when adjusted net income exceeds £100,000. It reduces by £1 for every £2 of income above £100,000 and can reach zero at £125,140.
Suppose an employee earns £55,000 during the 2026/27 tax year and receives the standard Personal Allowance of £12,570.
Their taxable income would be:
£55,000 − £12,570 = £42,430
The first £37,700 of taxable income would generally be taxed at 20%.
The remaining:
£42,430 − £37,700 = £4,730
would fall into the higher-rate band and be taxed at 40%.
This means the employee does not pay 40% tax on their entire £55,000 salary. The 40% rate applies only to the £4,730 that falls within the higher-rate band. The example shows why entering the 40% tax bracket does not mean your whole salary is suddenly taxed at 40%.
For taxpayers in England, Wales and Northern Ireland with the standard Personal Allowance, the higher-rate threshold is effectively £50,270 of gross income.
This is because:
£12,570 Personal Allowance + £37,700 basic-rate limit = £50,270
Once taxable income moves above the relevant threshold, the portion within the higher-rate band is generally taxed at 40%.
However, the calculation can become more complicated if you have:
Therefore, simply looking at your salary may not always give you a complete picture of your tax position.
The £100,000 level is particularly important because the Personal Allowance starts to reduce once adjusted net income exceeds £100,000.
For every £2 of adjusted net income above £100,000, £1 of the Personal Allowance is withdrawn. This means someone earning between £100,000 and £125,140 can face a more complicated effective tax position because they are both within the higher-rate band and gradually losing their tax-free allowance.
For example, if your adjusted net income is £110,000, the amount above £100,000 is £10,000.
The Personal Allowance reduction would be:
£10,000 ÷ 2 = £5,000
So, instead of receiving the full £12,570 Personal Allowance, you would have £7,570.
This is why tax planning can become increasingly important as income approaches or exceeds £100,000.
Not necessarily in the same way as employment or self-employment income.
Savings income and dividends have their own tax rules and rates. For 2026/27, dividend income above the £500 dividend allowance is taxed at different rates depending on the taxpayer's Income Tax band. The higher-rate dividend tax rate is 35.75%.
Similarly, savings income can be subject to different allowances and rules.
Therefore, someone with employment income, savings and dividends may need to consider the interaction between several types of income rather than applying a simple 40% calculation to everything.
Depending on your circumstances, certain legitimate tax-planning arrangements may affect your taxable income or tax liability. Pension contributions, for example, can be relevant to tax planning, although the rules and treatment depend on the type of contribution and your individual circumstances.
If you are self-employed, keeping accurate records of allowable business expenses can also help ensure that your taxable profits are calculated correctly.
It is important not to make financial decisions solely to avoid entering the 40% tax bracket. Paying a higher rate on part of your income does not mean that earning additional income leaves you worse off overall.
Instead, consider your complete financial position and seek professional advice where necessary.
The higher-rate band can also affect self-employed professionals and business owners.
For example, a sole trader may have employment income alongside profits from self-employment. These sources can contribute to their overall taxable income and potentially move part of their income into the higher-rate band.
Accurate bookkeeping and timely tax calculations can therefore be particularly useful. Keeping income and expenses organised throughout the year can make it easier to estimate your tax liability and prepare for Self Assessment payments.
Understanding the 40% tax bracket is important when your salary, business profits or combined income approaches the higher-rate threshold. Moving into the 40% band does not mean your entire income is taxed at 40%. For 2026/27, the standard Personal Allowance is £12,570, with higher-rate tax applying to relevant income above the basic-rate band.
If you are unsure how the higher-rate band affects you, PHS Associates can help you understand your tax position and organise your financial records. We provide professional UK accounting and tax support tailored to your circumstances. Book a free consultation today for reliable guidance with your tax affairs.

PHS Associates Acc & Co is led by a skilled team with expertise in Accounting, Taxation, Payroll, Business consultancy, and Company secretarial services.
© Copyright 2026 PHS Associates Acc & Co
Company number - 08670151